Home › BRRRR & refinance analyzer
BRRRR · US & CanadaBRRRR & cash-out refinance analyzer (US & Canada)
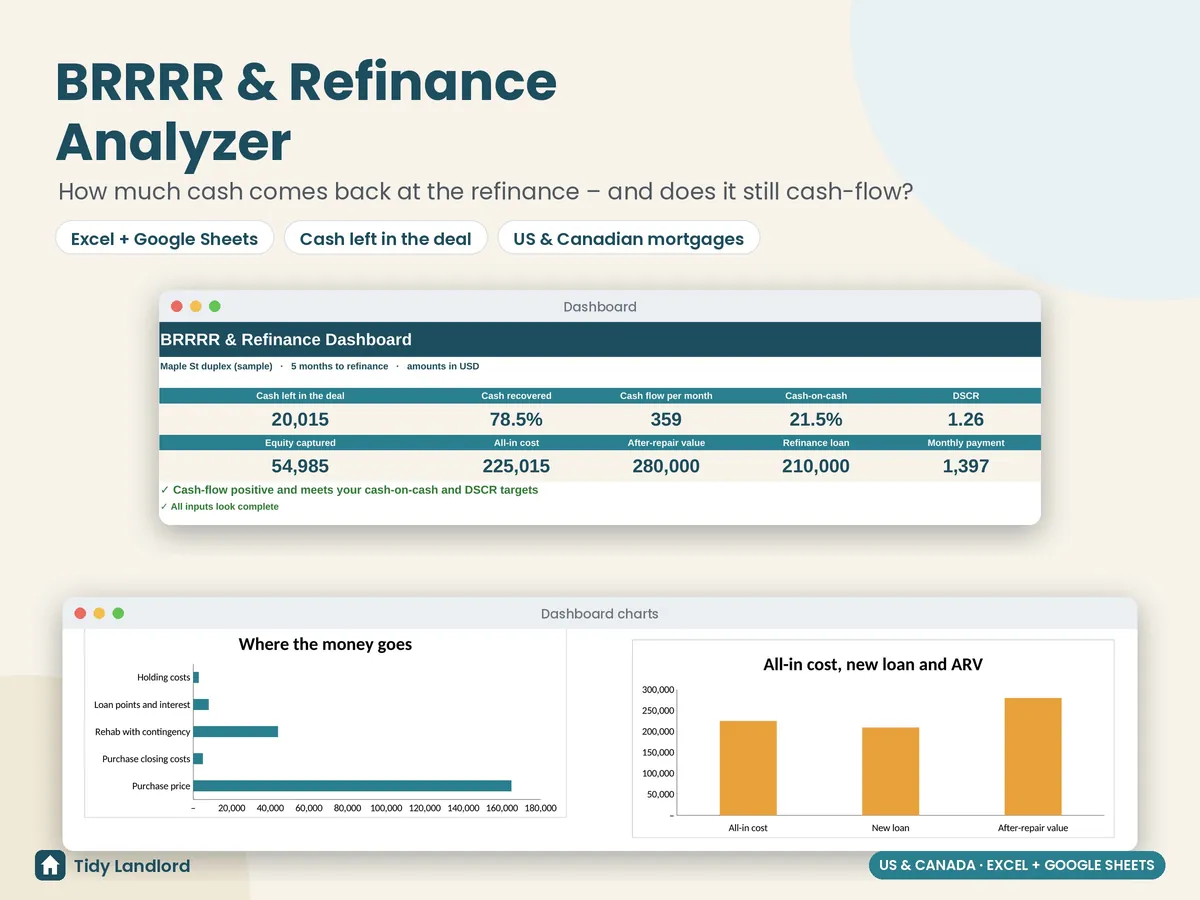
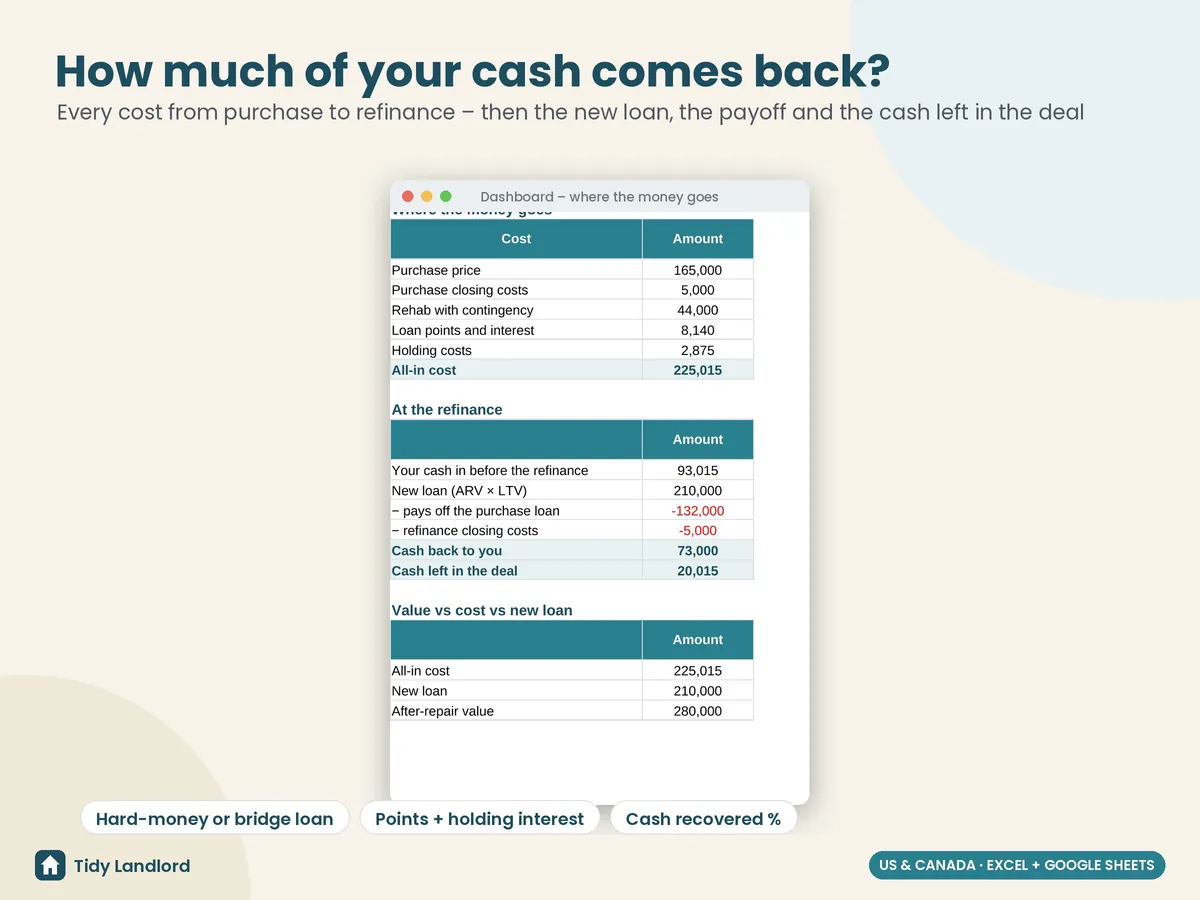
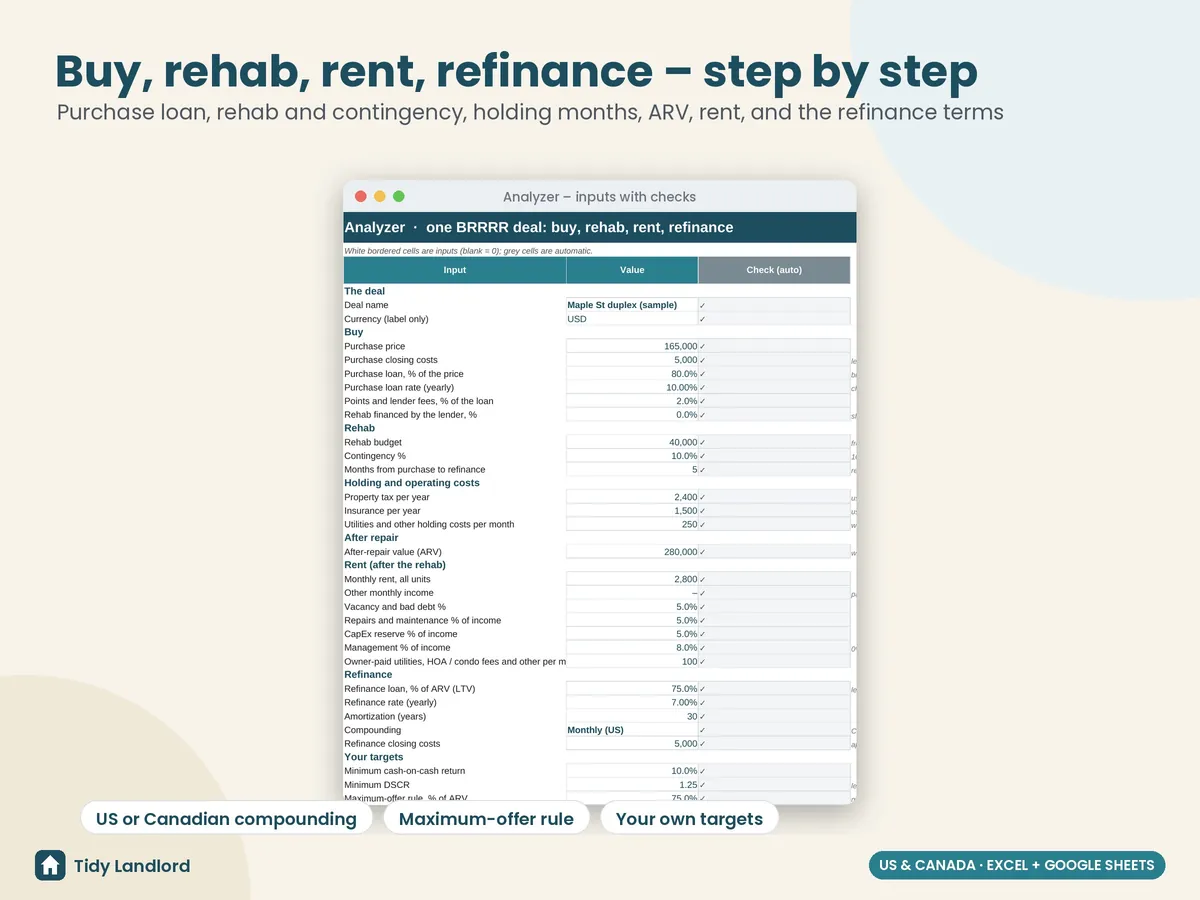
How much of your cash comes back at the refinance, and does the rental still pay afterwards? Run the numbers on a BRRRR deal (buy, rehab, rent, refinance, repeat) before you make the offer. Enter the purchase and its financing, the rehab, how long you'll hold before refinancing, the after-repair value (ARV), the rent and the refinance terms, and this workbook shows your all-in cost, the cash you put in, the new loan, the cash back, the cash left in the deal, monthly cash flow, cash-on-cash return, DSCR and equity captured. Works in Excel and Google Sheets.
Instant digital download (.xlsx). No macros, no subscription.
Included in both complete bundles: get this spreadsheet plus 19 more in the Complete Landlord Bundle (US) (CA$84.99, save about 75%) or the Canadian Landlord Bundle (T776) (CA$86.99, save about 74%).
What you get
- An analyzer with one deal on one page: purchase price and closing costs, purchase loan % and rate, points and lender fees, rehab financed by the lender, rehab budget and contingency, months from purchase to refinance, property tax, insurance and utilities while you hold, ARV, rent and other income, vacancy, repairs, CapEx and management %, owner-paid costs, the refinance (LTV, rate, amortization, compounding, closing costs) and your targets
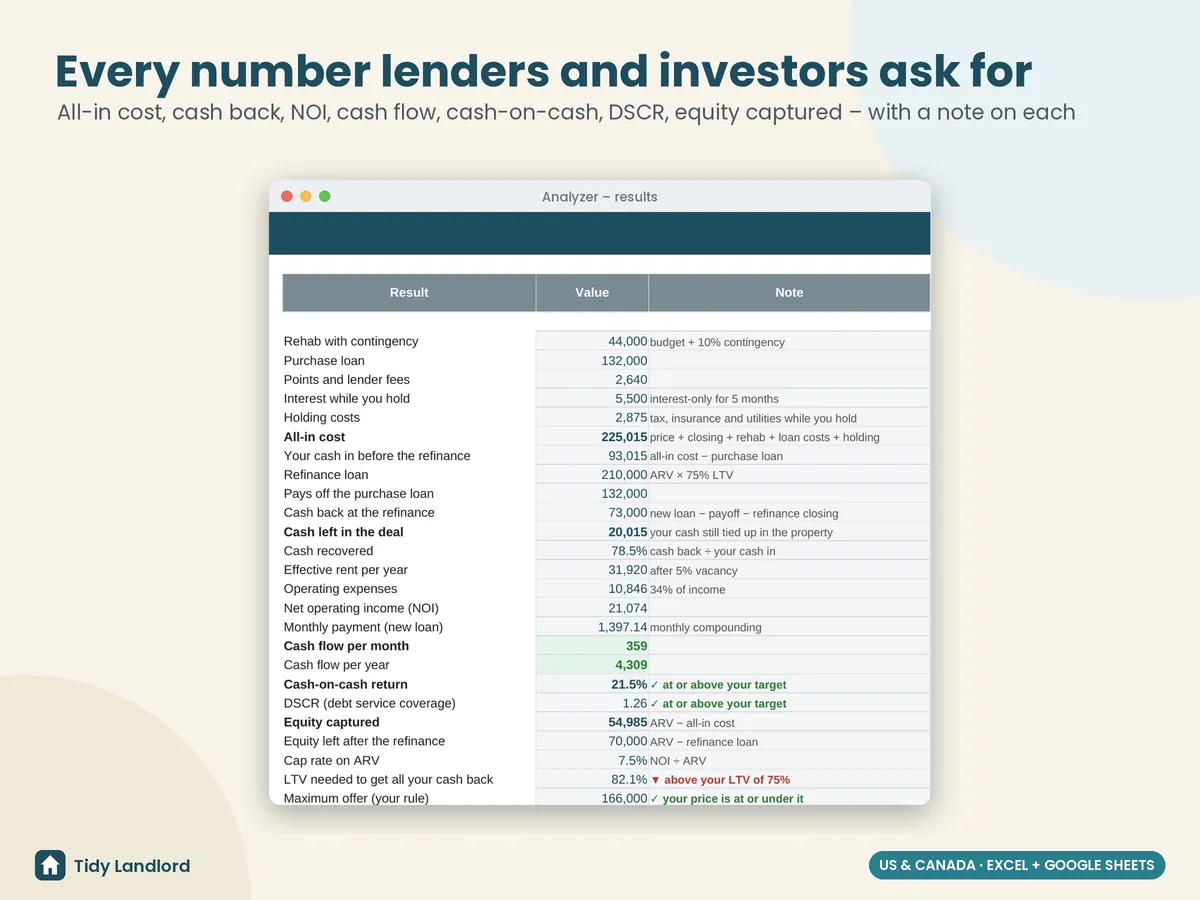
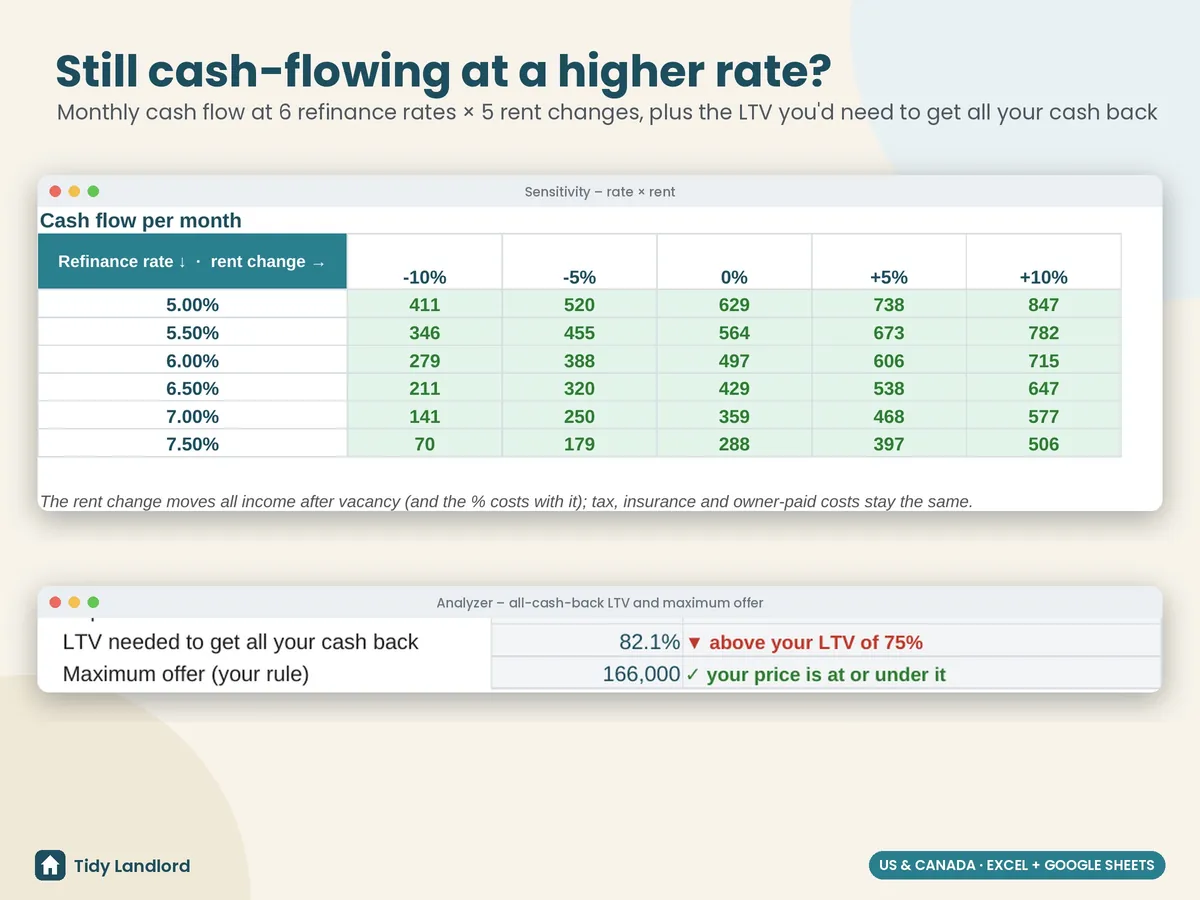
- Results for that deal: all-in cost, your cash in, refinance loan, payoff, cash back, cash left in the deal, cash recovered %, NOI, monthly payment, cash flow per month and per year, cash-on-cash, DSCR, equity captured, cap rate on ARV, the LTV you'd need to get all your cash back and the maximum offer under your rule (for example 75% of ARV minus rehab), each with a ✓ or ▼ against your target
- Hard-money or bridge loans with points and a lender-funded rehab, a conventional purchase loan, or all cash
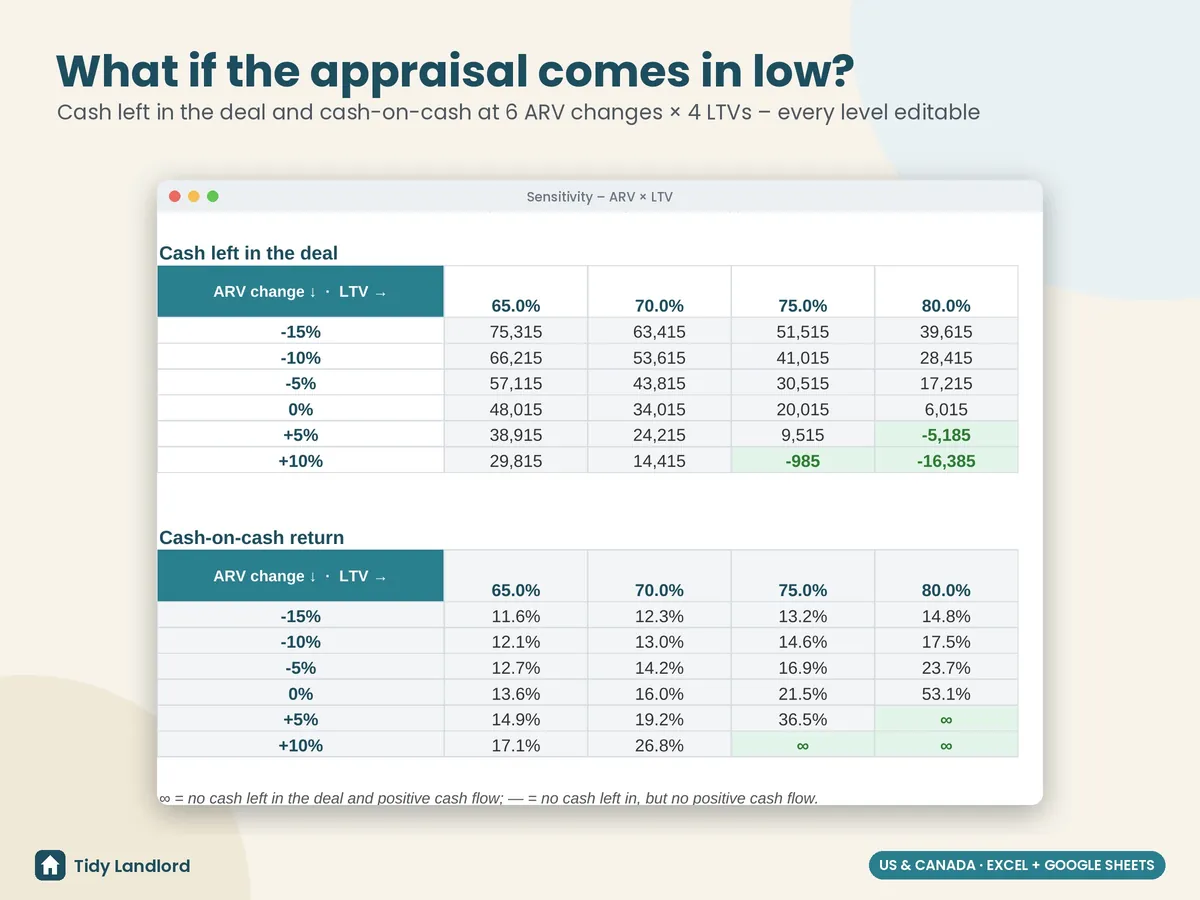
- Sensitivity: cash left in the deal and cash-on-cash at 6 ARV changes (appraisal −15% to +10%) × 4 refinance LTVs, and monthly cash flow at 6 refinance rates × 5 rent changes; every level editable
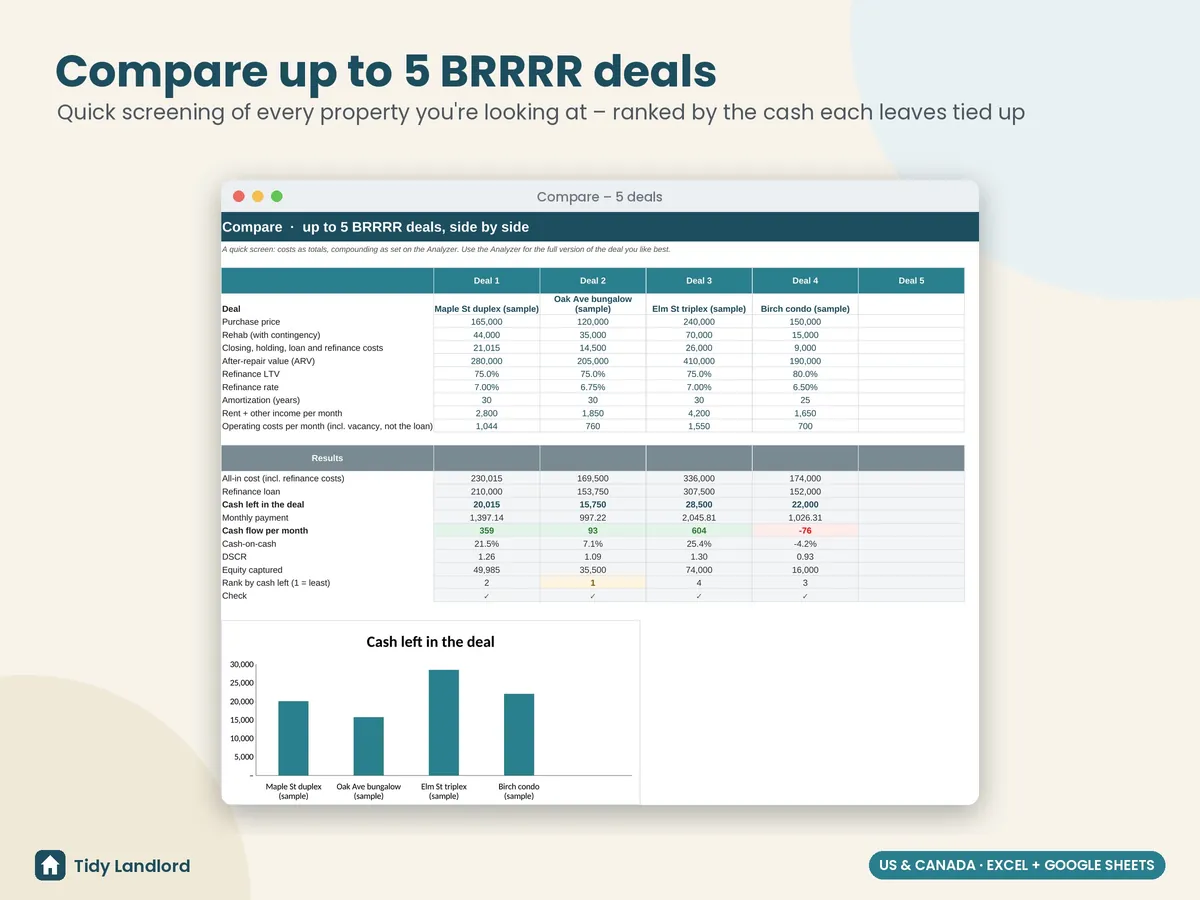
- Compare: up to 5 BRRRR deals side by side, ranked by the cash each leaves tied up, with a chart
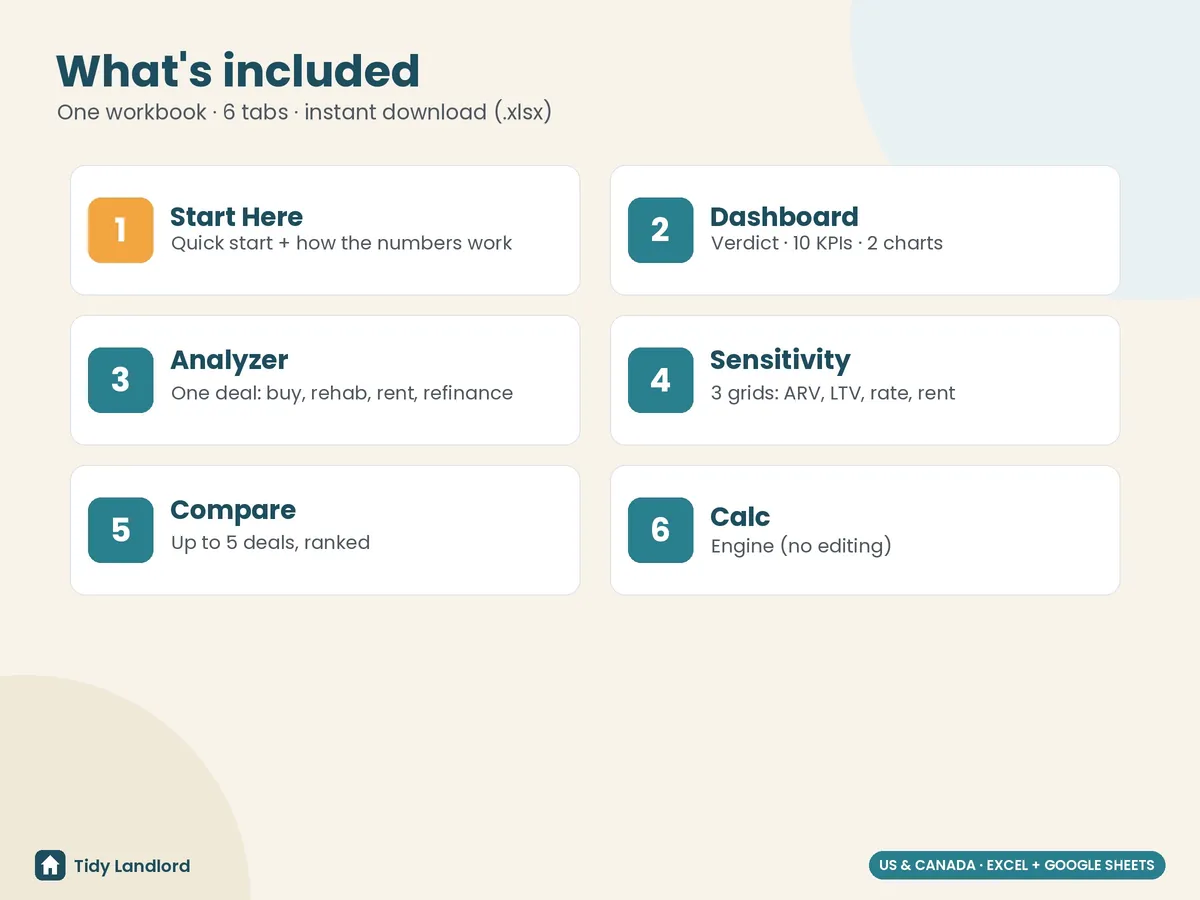
- A dashboard with a one-line verdict, 10 key numbers, where the money goes and what happens at the refinance, with two charts
- Check columns that flag text in number cells, percentages over 100%, rates over 30%, a missing price or ARV, an ARV below the purchase price and more; the dashboard counts them for you
- A Start Here guide in plain English, to analyze your first deal in about 10 minutes
Details
- How the numbers work: all-in cost = price + closing costs + rehab × (1 + contingency) + points + interest while you hold + holding costs; your cash in = all-in cost − purchase loan; new loan = ARV × LTV; cash back = new loan − payoff − refinance closing costs; cash left in the deal = your cash in − cash back; cash-on-cash = yearly cash flow ÷ cash left in the deal; DSCR = NOI ÷ yearly loan payments; equity captured = ARV − all-in cost
- US monthly or Canadian semi-annual mortgage compounding; any currency label
- Excel 2010+ and Google Sheets, no macros, no add-ons, no subscription
- Tested formula by formula in LibreOffice against an independent model (US and Canadian mortgages checked against standard payments, a hand-worked deal, all cash, all cash back, bringing cash to the refinance, a lender-funded rehab, a losing deal, cleared data and edge cases)
- For deciding before you buy; to track the rehab itself, use the renovation & rehab budget tracker
Screenshots
How it works
- Buy on Etsy and download the .xlsx file.
- Open it in Excel, or upload it to Google Drive and choose File → Save as Google Sheets.
- Type over the clearly marked sample deal on the Analyzer (recent sold comparables are the best source for the ARV), then read the Dashboard and the Sensitivity grids.
Doing the rehab? Keep it on budget with the Rental Renovation & Rehab Budget Tracker (budget vs actual, contractor bids, draw schedule). Buying a turnkey rental instead? Use the Rental Property Investment Analyzer.
Free guide: The BRRRR method explained: the refinance math, step by step
This is an estimating tool, not financial, investment, tax or legal advice: results are only as good as your assumptions. The refinance depends on the appraisal and on the lender: lenders set their own maximum LTV, rates and debt-coverage rules, and many require a waiting (seasoning) period before they lend on the after-repair value, so check with your lender before you buy. Income tax, depreciation or CCA, prepayment penalties and rate changes at renewal aren't included. It was designed with the help of AI tools, then reviewed and tested before release.